Switching from umowa o pracę to B2B: a step-by-step plan and the tax trap
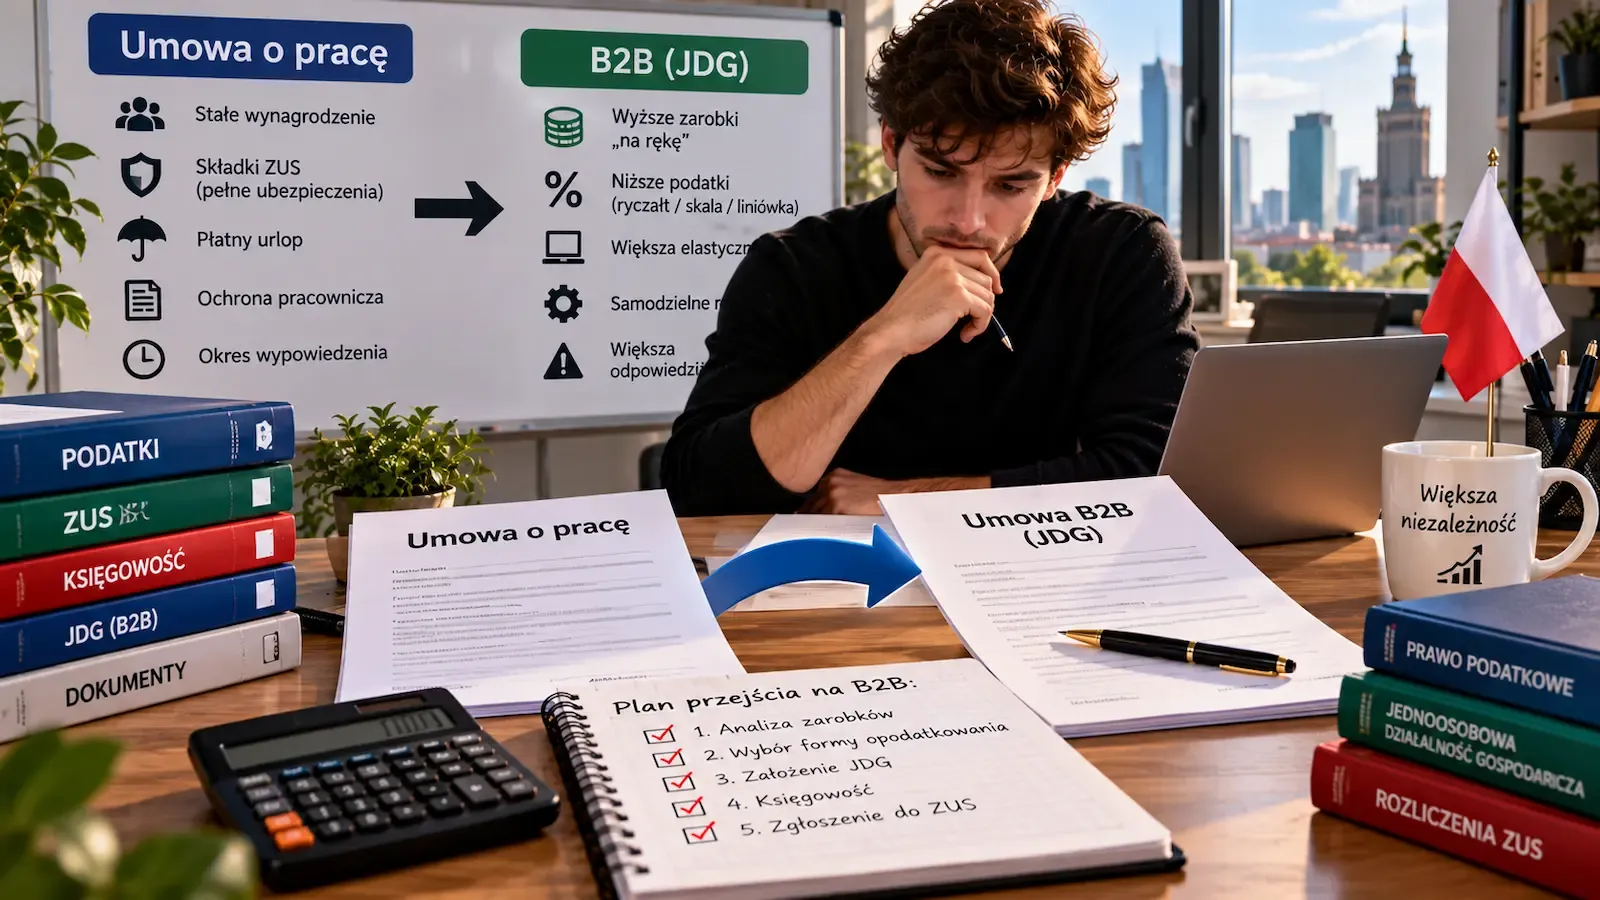
Your employer suggests: "Switch to B2B — you'll take home a thousand more." Sounds like a raise for free. For an experienced programmer, driver or builder it really can pay off. But there's one trap that makes some people pay more tax after switching than they expected.
A common belief is that on B2B you can simply choose the 19% flat tax and forget about the scale. That's not true if you provide services to your current or former employer — in the same scope as on your employment contract. In that case the flat tax and ryczałt aren't available for that income.
Step 1. Check whether you can open a JDG
Not every foreigner can register a jednoosobowa działalność gospodarcza on the same terms as a Polish citizen. Those who can include:
- Ukrainian citizens staying legally under the special act (UKR status) — while those rules apply.
- Holders of a karta stałego pobytu or EU long-term resident status.
- Holders of some temporary residence cards — e.g. issued after graduating from a Polish university or on the basis of marriage to a Polish citizen.
If your karta pobytu was issued for work on an employment contract with a specific employer, switching to B2B may require changing the basis of your stay. Check this before you resign.
Step 2. The flat-tax trap
The law bars choosing the flat tax (19%) for income from services provided to an employer you worked for on an employment contract this year or last year, if the services match what you did as an employee. The same applies to ryczałt.
- Consequence. That income is taxed on the scale: 12% up to 120,000 zł a year and 32% above it.
- When it's allowed. If a full tax year has passed without an employment contract with that company, or if the B2B services are substantially different.
- Other clients. The rule doesn't apply to new clients you were never employed by.
Step 3. Registering in CEIDG
- CEIDG-1 form — online at biznes.gov.pl, free. You need a profil zaufany or a visit to the municipal office (gmina).
- PKD codes — your type of activity. They affect your ryczałt rate and some obligations.
- Tax form — scale, flat or ryczałt. You can state it right in the form.
- Business bank account — not mandatory for a JDG, but very handy and needed for the VAT "white list".
Step 4. ZUS: relief in the first years
- Ulga na start — the first 6 full months without social contributions, only health.
- Preferencyjny ZUS — reduced social contributions for the next 24 months.
- Full ZUS — after that.
Important: ulga na start isn't available if you provide your former employer with the same services you did as an employee this year or last year. The condition is similar to the tax trap.
Step 5. Count what you lose
B2B isn't "a job with a bigger salary". These disappear:
- Paid holiday — unless the B2B contract includes "paid break days".
- Sick pay — only with voluntary chorobowe contributions and after 90 days of insurance.
- Protection from dismissal — a B2B contract ends the way the contract itself says.
- Accounting — you'll pay an accounting office or service, usually from a few hundred złoty a month.
Don't compare gross with gross — compare take-home pay after tax, ZUS and accounting, allowing for 26 unpaid days.
Step 6. The B2B contract
Before signing, check the termination notice, paid rest days, invoice payment terms (14 or 30 days) and liability for mistakes. If in practice you work like an employee — fixed hours, a manager, a desk in the office — it's a risk for both you and the company.
Checklist before switching to B2B
- Right to a JDG. Check whether your residence status allows self-employment.
- Tax. If the client is your employer, expect the scale, not 19%.
- ZUS. Find out whether you qualify for ulga na start.
- Accountant. Arrange one before registering, not after your first invoice.
- Comparison. Work out net take-home including holiday and sick pay.
- Contract. Read the termination and rest-day clauses.
Subscribe to our newsletter:
Latest Posts:
Latest Posts:
Personal pronouns in Polish: go or jego, cię or ciebie, do niego, z nią
Verbs and their cases in Polish: szukam pracy, pomagam koledze, czekam na autobus
Addressing people in Polish: Panie Marku, Pani Anno, Aniu — the vocative
Comparatives and superlatives in Polish: lepszy, tańszy, najlepszy, im więcej — tym więcej